Form OTN-1 · Register
Loading the Register.
Form OTN-2
Get the
new issue.
Monthly intel on jurisdictions, structures, and entity strategy for builders in crypto and tech.
Form OTN-1 · Register
Loading the Register.
Form OTN-2
Monthly intel on jurisdictions, structures, and entity strategy for builders in crypto and tech.
Form OTN-3 · Entry of record
Register / Capital Formation / Entry OTN-2025-004
This is to certify that the entry
was filed in the Register on 28 February 2025, under the jurisdictions Capital Formation, VC, Crypto, Investing and Web3 Entrepreneurship.
Standfirst
In this post, we take a matter-of-fact approach to equity capital, starting with an overview of recent trends, followed by a brief explanation of a standard Simple Agreement for Future Equity (SAFE), and closing with a discussion of a typical VC term sheet.
We’ve blogged on various occasions in the past about VC.
In June 2021, we wrote an ode and epitaph to VC, and more recently, in March 2024, we posted a brief review of “founder vs. investor”, a brutally candid book about how the relationship between Founder and investor is inherently fraught with friction.
Today’s post is less subjective and takes a matter-of-fact approach to equity capital, starting with an overview of recent trends, followed by a brief explanation of a standard Simple Agreement for Future Equity (SAFE), and closing with a discussion of a typical VC term sheet.
SAFEs are a widely-used fundraising instrument for pre-seed, seed and even A round equity capital.
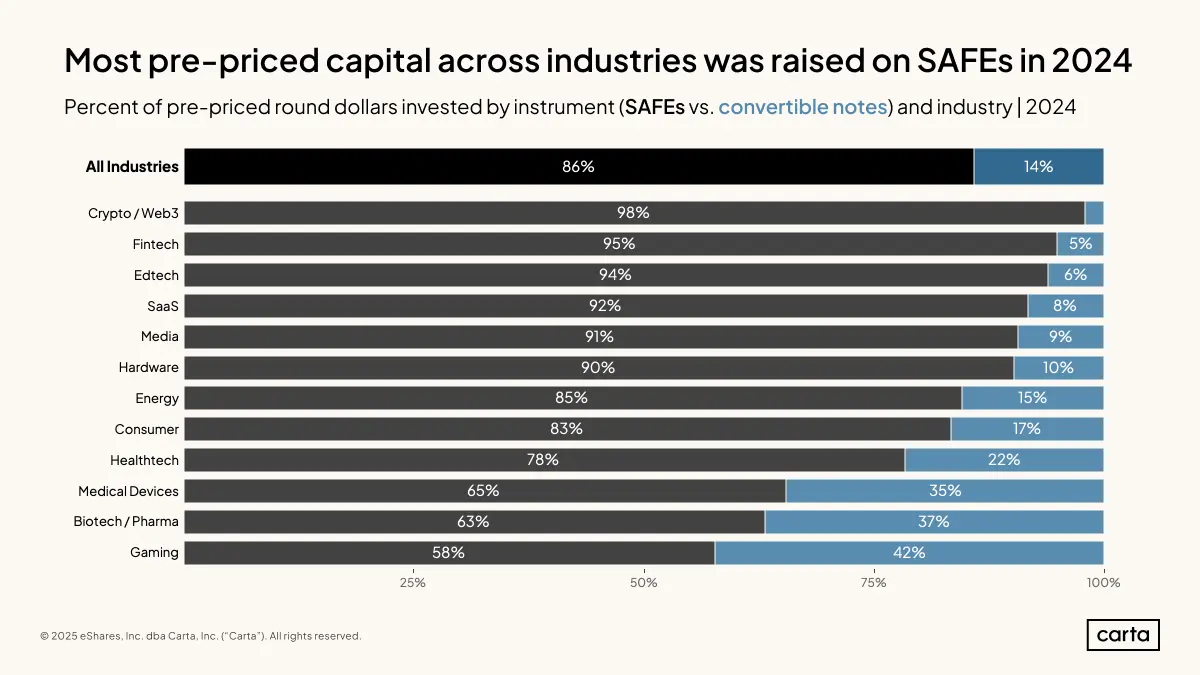
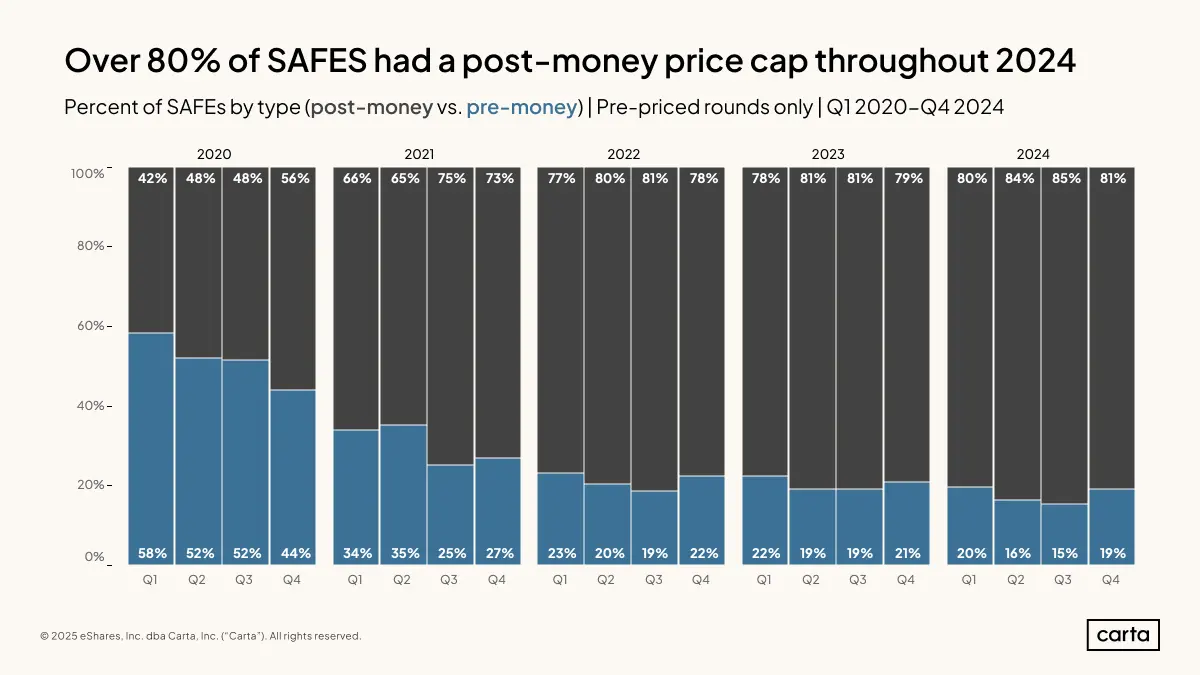
Carta’s 2024 State of Pre-Seed report indicates that most pre-priced rounds used SAFEs across industries, with crypto leading with 98%.
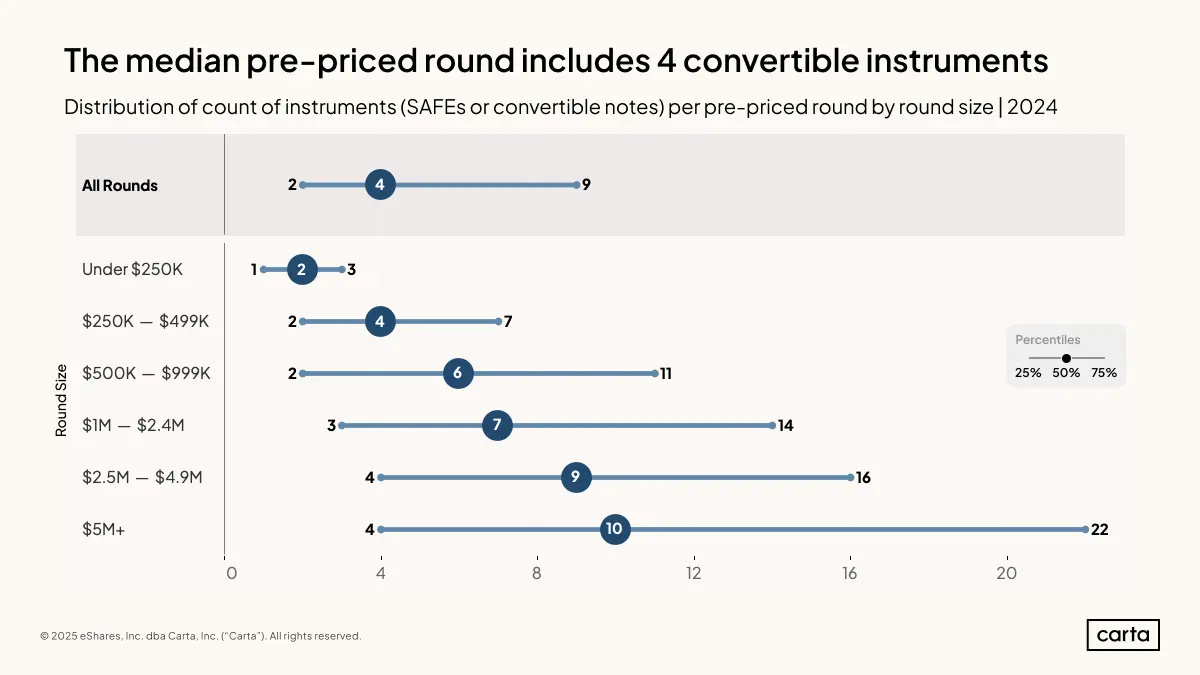
On average, projects use 4 convertible instruments (mostly SAFEs) before doing a priced round, with SAFEs raises starting at $250k to around $5MM.
What this means is that if you are looking to attract equity investors for your project, you will most likely be using a SAFE, possibly combined with a Token Warrant if at some point in the future your project will be issuing a native token.
In essence, a SAFE gives your investor the right to click into shares at a point in the future where the valuation of your company is established in what is called a “priced round”.
Key is that investors have visibility as to how many shares they will get, given that at the moment they invest, the company hasn’t priced its shares yet i.e. no valuation has to be agreed at the moment SAFEs are used.
This is a key attraction of using SAFEs, as agreeing on valuation with a cartel of investors can lead to prolonged back and forth, so SAFEs shortcut this process by creating a mechanism in which your investors are essentially given a formula by which they can calculate their future stake.
The easiest way to give your SAFE investors visibility on what % of the company they will eventually own is by using what is called a “post-money” SAFE.
No surprise perhaps that, according to Carta’s research, in 2024 over 80% of pre-priced rounds use post-money price caps:
Perplexity does a good job explaining the post-money price cap SAFE:
A post-money price cap in a SAFE is a predetermined maximum valuation at which an investor's investment will convert into equity. This cap takes into account the total amount of SAFE investments when calculating the company's valuation.
Key features of a post-money price cap in a SAFE include:
Quoted from the entry
“For example, if an investor provides $1 million with a post-money valuation cap of $10 million, they effectively lock in a 10% ownership stake in the company upon conversion, even if the company is priced at say $12MM at the time of the priced round, since SAFE holders will opt to use the lower cap rather the higher valuation for their conversion.”
— Otonomos, 28 February 2025
By contrast, a pre-money SAFE means valuation is effectively deferred until later financing rounds, creating uncertainty about an investor’s final ownership stake, as the amount of equity an investor receives is not fixed at the time of investment, making it harder to predict future ownership percentages. This becomes particularly problematic with multiple pre-money SAFE rounds, which will make it more challenging to track and calculate ownership stakes.
Other SAFE terms are pretty standardized and the number of key areas for Founders to be aware of are well documented. We list them here in summary:
When Web3 projects raise funds through a SAFE, investors typically anticipate receiving a token allocation that corresponds to their investment amount if the project intends to launch a token in the future.
The legal structure of this allocation is a Token Warrant, which is separate from the SAFE. This is distinct from a SAFT/E (Simple Agreement for Tokens and Equity), which presents legal challenges, at least within the U.S. The Warrant's purpose is to incentivize investors to participate in the SAFE, and therefore it must be legally separate from it.
The Token Warrant does however cross-reference the SAFE by giving the holder the right, but not the obligation, to receive or purchase a specific number of tokens at a predetermined price or under specific conditions, typically within a set timeframe.
The conversion mechanism into tokens under a Token Warrant outlines how this right is exercised and how the tokens are issued or delivered to the holder.
While such conversion varies depending on the terms set by the issuing entity (which is typically outside of the U.S., e.g. in the British Virgin Islands), here’s a general explanation of how it typically works:
As we’ve seen above, given that most SAFEs are issued with post-money cap, investors can easily calculate what % of tokens they are set to receive.
Key here is to define over what amount of tokens this % allocation will apply. We have seen terms where this calculation applies on all present and future tokens, which seems excessive, as this means SAFE investors would have to be continually topped up as more tokens get minted over the lifetime of the project.
A more restrictive approach is to only apply the conversion to the amount of tokens in “free float” at the moment of conversion, e.g. using the number of tokens offered for sale to the wide community, excluding any pre-mints and tokens held in reserve.
If the warrant isn’t exercised by the expiration date or if conditions aren’t met, it may expire worthless, meaning no tokens are issued. Some warrants might also include provisions for extension or alternative outcomes (e.g., a refund).
For a real-world analogy, think of a Token Warrant like a stock warrant in traditional finance, but adapted for digital assets. The conversion mechanism is essentially the "how and when" of turning that promise into actual tokens you can hold, trade, or use in a decentralized ecosystem.
In Web3 projects that involve both stockholders (traditional equity holders) and token holders (participants in the decentralized ecosystem), revenue flow is a bit of a hybrid beast, blending centralized corporate structures with decentralized tokenomics.
The exact path depends heavily on the project's design—its legal setup, governance model, and how it defines the roles of stocks and tokens.
Here’s a breakdown of how it generally works:
1. Revenue Generation
Web3 projects typically generate revenue through activities like transaction fees (e.g., on a blockchain protocol), service fees (e.g., DeFi platforms or NFT marketplaces), subscriptions, or partnerships. This revenue usually flows into the project’s treasury or operational entity, which could be a traditional company (like a Delaware C-Corp) or a decentralized autonomous organization (DAO), depending on how it’s structured.
2. Stockholders’ Share
Stockholders are tied to the centralized, legal entity behind the project—think of it as the "Web2" side. Revenue allocated to them follows traditional corporate finance principles:
For example, if a Web3 project like a blockchain gaming company generates $10 million from in-game NFT sales, the parent company might take a cut (say, $3 million) to cover costs and distribute profits to stockholders.
3. Token Holders’ Share
Token holders participate in the decentralized, "Web3" side of the project, and their revenue flow is tied to the token’s utility and governance design:
Using the same gaming example, the remaining $7 million might flow into a DAO treasury, where token holders vote to allocate it—say, 50% to staking rewards and 50% to game development, by way of grants out of the project’s decentralized Foundation.
4. The Split: Tension and Balance
The tricky part is how revenue gets divided between stockholders and token holders, which isn’t always clear-cut:
5. Practical Examples
Learning to live with schizophrenia
We blogged a while back (February 2022) about the schizophrenia at the heart of projects that issue equity and tokens.
Revenue in these hybrid Web3 projects flows like a river with two tributaries—one feeding the traditional stockholder bucket (profit, equity growth) and the other the token holder bucket (rewards, ecosystem value).
The split depends on how the project balances centralized control with decentralized participation. If the company prioritizes shareholders, token holders might get less direct revenue but benefit from ecosystem growth. If it leans Web3-native, token holders might see more immediate returns, while stockholders rely on long-term equity gains.
As discussed above, at the moment of a priced round, all your SAFE investors will convert into stock of your company using the conversion formula of the SAFE (typically on post-money terms).
If the company’s valuation is lower than the SAFE cap, the amounts under the post-money SAFE will be used as the nominator over the post-money valuation in the denominator to calculate the stake SAFE holders will have in the company once everything is said and done. Employee Share Options Plans too will come into the picture here and whilst Founders prefer to add them so everybody dilutes , investors often like to see the ESOP priced in before they calculate how much ownership of the company their investment will secure.
In summary, much will be open for negotiation, typically with a lead investor who agrees the terms and invests the bulk of the money, with other investors following on the same terms.
Much has been written and is researchable when it comes to termsheets and pitfalls for Founders.
A helpful heuristic is to divide the terms of a VC termsheet into clauses that deal with the economics of the investment and those that secure governance control.
We all read the horror stories of founders who, after years of eating glass, have no upside left when the project they built exits, or who get booted out by investors in mid-flight.
Typically, such unhappy outcomes are the result of the interplay of economic and governance clauses of the Term Sheet which then find their way into the long-form Stockholder Agreement.
As a founder, navigating this Term Sheet can feel like deciphering a foreign language—except the stakes are your company’s future!
The terms dictate how much control, equity, and economic upside you’ll retain, so it’s worth understanding the key ones that could trip you up or protect you.
Here’s a rundown of the typical terms you should zero in on, explained in a way that cuts through the jargon:
As with the SAFE, here too pre- vs post-money is the starting point: how much your company is worth before (pre-money) and after (post-money) the VC’s investment. A higher valuation sounds great—it means less equity given up—but watch out for inflated numbers that set unrealistic expectations for future rounds. If the VC pushes for a $10M pre-money valuation on a $2M investment, your post-money is $12M, and they own ~16.7% (2MM over 12MM). Negotiate hard here, but know it’s a balance—too high, and you risk a down round later.
This decides who gets paid first if the company is sold or shuts down. A “1x liquidation preference” means VCs get their investment back before anyone else sees a dime. Watch for “participating” preferences (e.g., 1x plus a share of the leftovers)—it’s a double-dip that can leave founders with crumbs in a modest exit. Push for non-participating if you can; it’s fairer.
VC often want a board seat to influence decisions. A typical setup might be 3 seats: one for the founder, one for the VC, and one “independent.” Be cautious if they push for control, and be wary of agreeing to too many matters which will always need the VC Board Member to agree on, irrespective of the Board composition. You want a Board that advises, not dictates. Retaining a founder-friendly majority or at least a tiebreaker is key early on.
With vesting, even your own equity isn’t safe. VCs might insist on a 4-year vesting schedule with a 1-year cliff for founders, meaning you earn your shares over time. Yes you read that right: Even though you started out with 100% of Stock when you formed your C-Corp, you’re not building down from your equity but instead have to earn ownership of your own company. So if you’ve already been grinding for years, argue for “credit for time served” to accelerate this. Otherwise, leaving early - especially if VCs find Cause, which they can by fabricating allegations of misconduct - could cost you big: You will likely forfeit even the equity that vested in the past, meaning VCs can grab all your Founder shares and dole it out to anybody they think is better placed to run the business.
If your next round is at a lower valuation (a “down round”), this protects VCs by giving them more shares to offset the hit. “Full ratchet” is brutal—it adjusts their price to the new low, massively diluting you. “Weighted average” is gentler and more common. Fight for the latter; full ratchet is a red flag.
VC often require a chunk of equity (e.g., 10-20%) to be set aside for future hires before their investment. If it’s carved out of your pre-money valuation, it dilutes you, not them. Push for it to come post-money or be smaller—every percent matters.
These are veto powers VCs get over big moves—think selling the company, raising more money, or changing the charter. It’s reasonable for them to protect their investment, but if the list is too long (e.g., approving every hire), it handcuffs you. Negotiate to keep operational freedom.
This lets VCs force all shareholders to sell if they approve a deal. It’s meant to avoid holdouts, but if the threshold is too low (say, 50% of Preferred Stockholders, which is the class of Stock VC typically gets whilst you’ll hold Common Stock), you could be dragged into a sale you hate. Aim for a higher bar, like 75%, and ensure Founders have a say.
VCs might secure the right to invest in future rounds to maintain their ownership percentage. Fine in theory, but if they’re the only ones with cash at the table later, it can squeeze out new investors. Consider capping this or making it optional.
Once you sign a Term Sheet, this locks you into exclusive talks with the VC for 30-60 days. It’s standard, but a long window (90 days) or vague terms can trap you if they drag their feet. Keep it short and tight—30 days max.
These terms aren’t just legalese—they shape your leverage, payout, and autonomy. The VC’s goal is to de-risk their bet; yours is to keep enough skin in the game to make it worth the grind. Get a good lawyer who’s seen these deals before - ideally one who is not in the pocket of VC - and don’t be afraid to push back, especially on valuation, liquidation, and control. It’s your company, at least for now. Be strategic about the terms that matter for the stage you’re at.
Go to Part II: How to raise from the community in an unscammy way
Quoted from the entry
“Schedule a call with Otonomos before you raise.”
— Otonomos, 28 February 2025
Schedule today
Form OTN-2
Monthly intel on jurisdictions, structures, and entity strategy for builders in crypto and tech.
End of entry OTN-2025-004
Filed by Otonomos
| Filed |
| OTN-2025-005 | No cover on file | Part II. How to raise from the community in an unscammy way In this post, we give an overview of the key approaches, from the early days of Initial Coin Offerings (ICOs) to the more recent Fair Launch model, laid out in a way that tracks… | 01 | Filed |