Form OTN-1 · Register
Loading the Register.
Form OTN-2
Get the
new issue.
Monthly intel on jurisdictions, structures, and entity strategy for builders in crypto and tech.
Form OTN-1 · Register
Loading the Register.
Form OTN-2
Monthly intel on jurisdictions, structures, and entity strategy for builders in crypto and tech.
Form OTN-3 · Entry of record
Register / Entry OTN-2024-025
This is to certify that the entry
was filed in the Register on 31 August 2024.
Standfirst
The strange landscape of DAO legal structures recently acquired a permutation of the DAO LLC: the Decentralized Unincorporated Non-Profit Association or DUNA. In what follows, we're doing a deep dive and weigh its pros and contras. The State of Entitylessness DAOs generally either do not make use of a legal entity (an “entityless” structure) or they adopt an ownerless foreign foundation structure. The entityless structure leaves all three of the key issues facing DAOs unresolved: 1. No…
The strange landscape of DAO legal structures recently acquired a permutation of the DAO LLC: the Decentralized Unincorporated Non-Profit Association or DUNA.
In what follows, we're doing a deep dive and weigh its pros and contras.
DAOs generally either do not make use of a legal entity (an “entityless” structure) or they adopt an ownerless foreign foundation structure.
The entityless structure leaves all three of the key issues facing DAOs unresolved:
As a result, many decentralized projects have wrapped themselves in a foreign foundation legal skin, most typically in the Cayman Islands which allows for "founderless" foundations.
However, despite addressing the three shortcomings of entitylessness above, the Cayman founderless foundation comes with its own set of issues, including that:
Aiming to address the above shortcomings, and driven by clear impetus from corners of the U.S. venture capital community - who had invested in projects with foreign foundations, which have unclear tax and reporting treatment - Wyoming signed the DUNA into law on 7 March of this year, with it taking effect on 1 July 2024.
In what follows, we dissect key aspects of the DUNA, particularly in comparison to a foreign foundation.
In what follows, we do a deep dive on DAO legal structures including the DUNA, borrowing heavily from - but also commenting on - A16Z's "The DUNA: An Oasis for DAOs" and the 3-part "Legal Framework for DAOs" guide it commissioned on the subject (Part I, Part II and Part III).
In our view, the first filter when deciding whether to remain entityless as a DAO or adopt a legal skin is whether the DAO has significant U.S. membership.
Having significant U.S. membership in a DAO limits the feasibility of foreign trust structures and foreign incorporated structures, such as foreign foundations, as these foreign entities trigger heavy reporting requirements and potentially unfavorable tax treatment for U.S. members.
One DAO wrapper - the Republic of the Marshall Islands' "DAO LLC" ("RMI DAO LLC") - may have the closest similarity to the DUNA. However, under U.S. taxation such an entity is generally treated as a Foreign Corporation (unless approved for tax-exempt status within the United States).
This, together with part of the U.S. venture capital community seeking "respectability" for its DAO portfolio projects with significant US members by seeking to give them a clearer tax and reporting treatment, largely explains the emergence of the DUNA in what many consider a jurisdiction "one can work with": Wyoming.
As noted earlier, high on the list of desirable properties for a U.S.-centric DAO legal skin was its ability to support decentralization, which means that it does not require traditional hierarchical elements like officers or boards of directors.
This makes DUNAs suitable for truly decentralized organizations, which - with a wink to the Howey test - are not controlled by a person or an affiliated group of persons, i.e. organizations whose success or failure does not depend solely on the managerial efforts of any person or affiliated group of persons.
As a result, the DUNA contemplates a baseline structure that does not include a management function, but instead allows for the selection of "administrators" with limited authorization to perform specific tasks authorized by the membership.
This categorization aligns the Model DUNAA (Decentralised Unincorporated Nonprofit Association Act) with applicable standards for decentralization under U.S. securities laws.
By contrast, foreign foundations, even in the Cayman Islands where they can be formed without a named founder, still need to designate an individual as the controller/contact/responsible person for the entity (in the absence of a single Ultimate Beneficial Owner).
Moreover, recent changes in Cayman's Beneficial Ownership regime now require such individual's details to appear on the Cayman Corporate Registry. Whilst this registry is nott publicly accessible, it is safe to assume that such details will be shared with law enforcement and government agencies, thereby greatly diminishing the anonymity of the Cayman Foundation.
Finally, in order to provide limited liability protection to a DAO, the structure of a foreign foundation requires off-chain actions to be taken by individuals (e.g., enforcers, foundation directors or trustees) at the direction of the DAO, typically by way of an on-chain vote.
This means that even though DAO members are not actual members (or owners) of the foreign foundation, and limitations on the level of trust placed in its board can be included in its organizational documents, the relationship between the DAO and the foreign foundation can never be entirely trustless, This reliance on a board or other off-chain entities may compromise the DAO’s decentralization.
Practically, foreign foundations, because of their nature and offshore residency, face difficulties in becoming fully operational in their own right, e.g. by establishing a workforce to run the project from within the foundation itself.
This risks making them overly dependent on the developer company (typically a C-Corp for U.S.-based teams) and compromising their degree of decentralization, in addition to potentially dragging the entire foreign structure into the U.S. regulatory and tax web.
Irrespective of the above, and the various ways of mitigating these issues, the legal requirement for a foreign foundation (whether Cayman or elsewhere) to have an appointed Director inherently prevents it from being a purely decentralized setup.
When the DUNA first came on the scene, many Web3 builders gasped at its not-for-profit nature.
However, a DUNA is not limited in its ability to generate profits; its "non-profit" status simply prevents it from paying dividends or making distributions to members (except for those permitted by statutes).
For instance, under the WDUNAA, a DUNA may
Quoted from the entry
“pay reasonable compensation or reimbursements of reasonable expenses to its members, administrators and persons outside the nonprofit association for services rendered, including with respect to the administration and operation of the nonprofit association, which may include the provisions of collateral for the self-insurance of the nonprofit association, voting or participation in the nonprofit association's operations and activities' (if doing so is authorized by the governing principles).”
— Otonomos, 31 August 2024
A DUNA may also
Quoted from the entry
“[...] confer benefits on its members or administrators in conformity with its common non-profit purpose; repurchase membership interests (to the extent authorized by the nonprofit association's governing principles); and make distributions of property to members upon winding up and termination of the decentralized unincorporated nonprofit association [...].”
— Otonomos, 31 August 2024
What a DUNA cannot do is straight dividending, i.e. granting its members the right to share in its profits or distributing profits in a manner analogous to equity distribution mechanisms.
Network and protocol DAOs should avoid mimicking traditional equity structures, as doing so could blur the distinction between governance tokens and securities, thereby offending both Gary (Gensler) and the IRS.
Instead, DAOs should focus on tokenomics that incentivize productive contributions, such as governance participation, staking, and capital contributions, which drive the long-term value of the network.
This approach aligns with the decentralized, participant-driven ethos of web3, optimizing value across the ecosystem, rather than prioritizing short-term profits.
Although the DUNA structure is relatively untested, existing case law on UNAs is instructive regarding the effectiveness of limited liability for decision-making members, and the WDUNAA explicitly affirms that a DUNA is a separate legal entity from its members.
Informal formation: DUNAs (like UNAs) are informal, with minimal administrative complexity and no mandatory filings with the Secretary of State (although there are optional filings), allowing operations with little oversight. Further, the limited case law on UNAs specifically contemplates the lack of formality of the members not being grounds for disregarding the entity's legal status.
Information rights: DUNA members and administrators have the right to inspect the association’s books and records, but since there is no requirement to maintain specific records (including member listings). Therefore, the information rights only apply to whatever records the association has chosen to maintain. If records are kept on distributed ledger technology accessible to members and administrators, such information rights should be easily met. Former members and administrators retain the right to access information they were entitled to during their involvement, though some restrictions on access and use may apply.
While many jurisdictions do not require domestic entities to publicly list memberships, they often still demand that legal entities collect certain information for compliance and tax reporting. For DAOs prioritizing member anonymity, this is crucial when selecting an entity structure.
Failure to comply with the formalities required for any entity structure can result in losing the key benefits associated with that entity, such as limited liability. For example, DAOs using LLCs are often required to maintain member records. While some jurisdictions do not mandate public disclosure of these records, if member records are required at the entity level, it could compromise the anonymity of members and limit the effectiveness of these structures as liability protection vehicles. Wyoming and Tennessee’s DAO laws offer some improvement by not explicitly requiring member listing disclosures, but it’s unclear whether these laws fully exclude the listing requirements typically associated with LLCs. Additionally, the legal framework has not fully addressed how decentralized organizations, where no one has access to membership information, would manage or waive such requirements, even with notice in the articles of incorporation.
The Corporate Transparency Act (CTA) now requires disclosure to FinCEN of all beneficial owners ("BO") upon registration of an entity, and of all members who own 25% or more of the entity on an ongoing basis.
As mentioned before (under 'Divided Tax'), issues may arise for DUNAs in relation to member anonymity when compensating members for their governance contributions.
The ease of compliance with applicable tax reporting and payment obligations varies hugely based on the DAO’s activities.
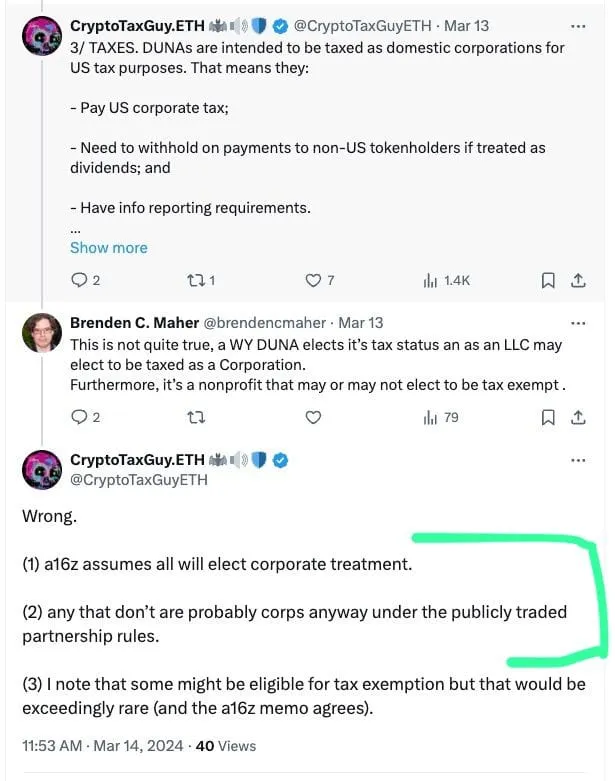
For DAOs using domestic U.S. entities such as the recently introduced DUNA, or the LLC, the tax reporting and payment requirements are quite clearly defined, and any complexity as to their treatment can be removed by electing corporate tax status, allowing entity-level taxation (see more on this below).
By contrast, DAOs with significant U.S. membership that opt for a foreign structure, such as an offshore foundation, may face more complex and potentially less advantageous tax obligations than they might initially anticipate.
Specifically, in relation to offshore foundations, there is uncertainty regarding how U.S. tax laws will ultimately treat them. If the IRS deems a DAO’s methods of directing foreign foundation directors to be leading to a mischaracterization, it may bring the DAO into the U.S. tax net, with potentially significant consequences.
The Appendix B of A16Z's second part DAO Legal Framework has a useful overview table for a number of DAO legal skins.
Entity-level taxation is an option for several of those DAO legal skins, including domestic U.S. entities such as the DUNA or the LLC.
Such election may be particularly valuable when flow-through taxation is administratively infeasible, mainly due to U.S. members of a flow-through organization being responsible for annual income reporting, whether or not distributions were made, but also because of desired anonymity by DAO members.
While a U.S. entity electing corporate tax treatment would face a 21% federal tax rate on profits, it simplifies reporting and payment obligations for individual members, limiting them to specific payments, transfers over $10,000, and distributions, if any.
Moreover, tax benefits from treaties are easier to manage at the entity level, avoiding the complexities of passing them through to members, which would require individual filings and varied withholding rates.
Tax-free jurisdictions offer significant benefits when offshoring internet-only activities away from the United States.
However, the presence of U.S. members contributing value to income-producing activities and exercising collective operational control diminishes the effectiveness of such offshoring strategies.
If a protocol is fully functional and independent of updates, maintenance, or support, using an offshore entity could allow tax optimization. However, without the specific and limited circumstances that would make this strategy applicable to DAOs, this strategy could be less optimized than U.S. corporate tax rates and expose the structure to scrutiny by other tax authorities.
For DAOs with significant U.S. membership, the benefits of foreign trust structures and foreign corporate structures are largely negated by laws designed to prevent U.S. citizens from using foreign entities to avoid taxes. Foreign trusts, for example, risk being classified as foreign grantor trusts if U.S. citizens exert control over the trust’s funding. This classification can trigger tax obligations on the initial transfer and make the grantors responsible for ongoing tax liabilities of the trust.
A DUNA may therefore present itself as an appropriate tax alternative to offshoring where tokenholders (a) conduct substantial business activities (not including voting) on behalf of the DAO from within the United States, or (b) expect US law, not code, to govern disputes.
The analysis runs as follows:
Despite the above, there may still be good tax reasons not to use a DUNA, for example:
Note that the above is based narrowly on tax considerations and does not take into account other factors. Also note that, specifically in relation to DUNAs making the tax partnership election, there is no precedent with the IRS or tax courts, and neither is there unanimity between practitioners, including those who have been privy to the creation of the WDUNAA itself!
As DAOs continue to push the boundaries of decentralized governance, the DUNA presents itself as a compelling middle ground between the freewheeling world of entityless structures and the rigid frameworks of traditional corporations.
It offers a path for DAOs to gain legal recognition, limited liability, and a more predictable tax regime - all while retaining their decentralized governance.
However, as with any sequel, the plot thickens. The DUNA comes with its own set of challenges, particularly around member requirements, profit distribution, and potential regulatory scrutiny. For some DAOs, it might be the perfect fit - offering just enough structure to keep regulatory retaliation at bay without stifling innovation. For others, especially those with complex international operations or a preference for anonymity, a foreign foundation might still be the safer bet (even if it means paying a little more in taxes if the DAO has U.S.-connected income and/or running the risk of being dragged into the U.S. tax net if there are U.S.-based DAO members who are involved with the DAO beyond mere voting).
In the end, choosing whether to get into the all-American hero DUNA skin or don the dark cape of a foreign setup comes down to the specific needs and goals of your DAO. If you’re looking to operate within the U.S., take investments from the U.S., or want more legal and tax certainty, the DUNA could be your superhero costume. This also explains why the DUNA has been promoted quite hard by corners of the U.S. venture capital industry who in the token heydays funded a lot of DAO projects without a proper setup, and who'd like to see a lot of offshore projects repatriated to the U.S.
However, as with any superhero movie, taking the role of a DAO comes with challenges and struggles and there are no guarantees of a happy ending.
So, whether you’re ready to embrace the DUNA or still debating whether this latest sequel is worth the watch, one thing is clear: the world of DAO legal structures is anything but boring, and there’s plenty more drama to come. Stay tuned!
Quoted from the entry
“> Book a call with Otonomos to weigh your options if you're a DAO.”
— Otonomos, 31 August 2024
Book FREE call
With special thanks toConall Fowler, Summer 2024 intern at Otonomos.
Form OTN-2
Monthly intel on jurisdictions, structures, and entity strategy for builders in crypto and tech.
End of entry OTN-2024-025
Filed by Otonomos